click below to login to your secure account
By
Tom Kozlik
Head of Public Policy and Municipal Strategy
Hilltop Securities Inc.
The municipal opportunity we identified two weeks ago has become even more compelling as tax-exempt yields and relative value indicators moved decisively higher. Others are taking notice.
Tax-exempt yields rose approximately 30 basis points last week, strengthening the municipal bond opportunity we first highlighted Sept. 14. Investors can now capture more tax-exempt income at more attractive relative valuations. The Bloomberg Municipal Bond Index was higher, closing Friday, Sept. 25, at 4.69%. Municipal-to-Treasury ratios also moved higher. We were enthusiastic about the opportunity two weeks ago. We are even more enthusiastic now.
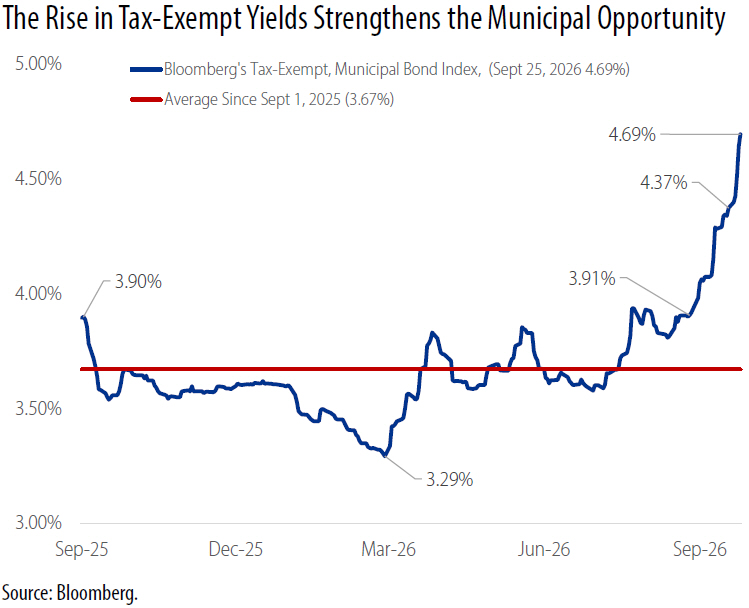
The market entered 2026 expecting lower interest rates. That outlook has been overtaken by persistent inflation, the conflict in the Middle East, concerns about federal debt, and a Federal Reserve that has provided less support and guidance than investors expected. We examined that shift in our August 27 commentary, The Market Thought Lower Rates Were Coming. Since August 27 The Bloomberg Municipal Bond Index rose 78 basis points from 3.91%.
Much of the increase in yields occurred last week alone. Where the index jumped 32 basis points to 4.69% from 4.37% the previous Friday. AAA Municipal Market Data (MMD) yields also rose sharply last week. The 2-year MMD yield jumped 42 basis points to 3.46%, the 10-year MMD yield rose 30 basis points to 4.05% and the 30-year MMD yield rose 18 basis points to 5.05%.
The speed of the move higher in yields is important, because it increased the income available to investors over such a short period. Investors do not need to identify the exact market bottom to recognize that the opportunity is better than it was two weeks ago.
Others are noticing. Burton Malkiel, author of A Random Walk Down Wall Street, reached a similar conclusion in a recent Wall Street Journal commentary. “Tax-exempt bonds today offer unusually high returns,” he wrote in It’s a Good Time to Buy Bonds.
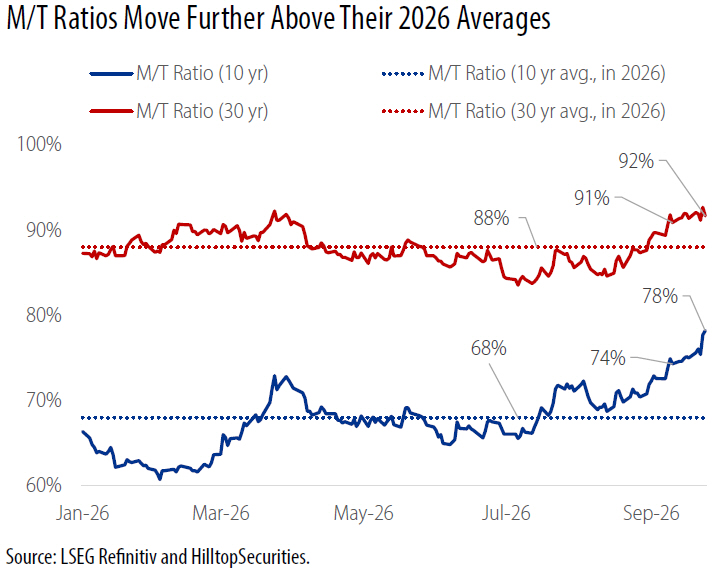
The 10-year Municipal-to-Treasury ratio (M/T Ratio) ended last week near 78%, well above its 2026 average of approximately 68%. The 30-year ratio rose to about 92%, also above its 2026 average of approximately 88%. These are among the most attractive M/T Ratios we have seen in 2026.
Those M/T Ratios measure municipal yields relative to Treasury yields at comparable maturities. Higher ratios generally indicate that municipal bonds offer more yield relative to Treasuries. The recent increase therefore adds a second source of value. Investors are not only receiving higher absolute tax-exempt yields. They are also receiving better relative value in today’s market.
That combination could broaden demand beyond traditional tax-exempt buyers, particularly if ratios remain elevated. It does not eliminate interest-rate risk or the need for disciplined credit selection. This steady improvement in M/T Ratios does make the municipal opportunity harder to overlook.
Municipal mutual funds reported a $1.8 billion outflow, per Lipper data, during the week ending Sept. 17, briefly interrupting one of the municipal market’s most important sources of demand. Fund flows then reversed, with approximately $633 million returning to municipal mutual funds last week. Investors have still added about $39 billion to municipal mutual funds in 2026.
The quick rebound confirms that investor demand remains strong, but it does not erase the effects of higher yields and recent market volatility. New primary market issuance must now come to market at yields attractive enough to draw buyers. This gives investors more income, greater choice, and more room to be selective. The current market backdrop may also make primary-market execution more difficult for issuers in the coming days and weeks.
Strong demand defined the municipal market for much of 2026 and remains an important source of support. The more immediate investor story, however, is the opportunity created by the speed and scale of the recent increase in yields. We identified that opportunity two weeks ago. Last week’s move made it materially better.
 As Head of Public Policy and Municipal Strategy, Tom Kozlik advises HilltopSecurities’ businesses and clients on strategies related to U.S. public policy, public finance, and infrastructure. He publishes regular commentary that provides insight into current trends affecting these themes across a variety of sectors and geographic regions. Kozlik is frequently featured in print, digital, and broadcast news segments and regularly offers his expertise as a keynote speaker and panelist at industry conferences and events across the country. He can be reached at 214.859.9439 or tom.kozlik@hilltopsecurities.com.
The paper/commentary was prepared by HilltopSecurities (HTS). It is intended for informational purposes only and does not constitute legal or investment advice, nor is it an offer or a solicitation of an offer to buy or sell any investment or other specific product. Information provided in this paper was obtained from sources that are believed to be reliable; however, it is not guaranteed to be correct, complete, or current, and is not intended to imply or establish standards of care applicable to any attorney or advisor in any particular circumstances. The statements within constitute the views of HTS Public Finance as of the date of the document and may differ from the views of other divisions/departments of Hilltop Securities Inc. In addition, the views are subject to change without notice. This paper represents historical information only and is not an indication of future performance. This material has not been prepared in accordance with the guidelines or requirements to promote investment research, it is not a research report and is not intended as such. Sources available upon request.
Hilltop Securities Inc. is a registered broker-dealer, registered investment adviser and municipal advisor firm that does not provide tax or legal advice. HTS is a wholly owned subsidiary of Hilltop Holdings, Inc. (NYSE: HTH) located at 717 N. Harwood St., Suite 3400, Dallas, Texas 75201, (214) 859-1800, 833-4HILLTOP.